


Blog
Does Credit Card Settlement Affect Credit Score? Impact on CIBIL & Future Loans

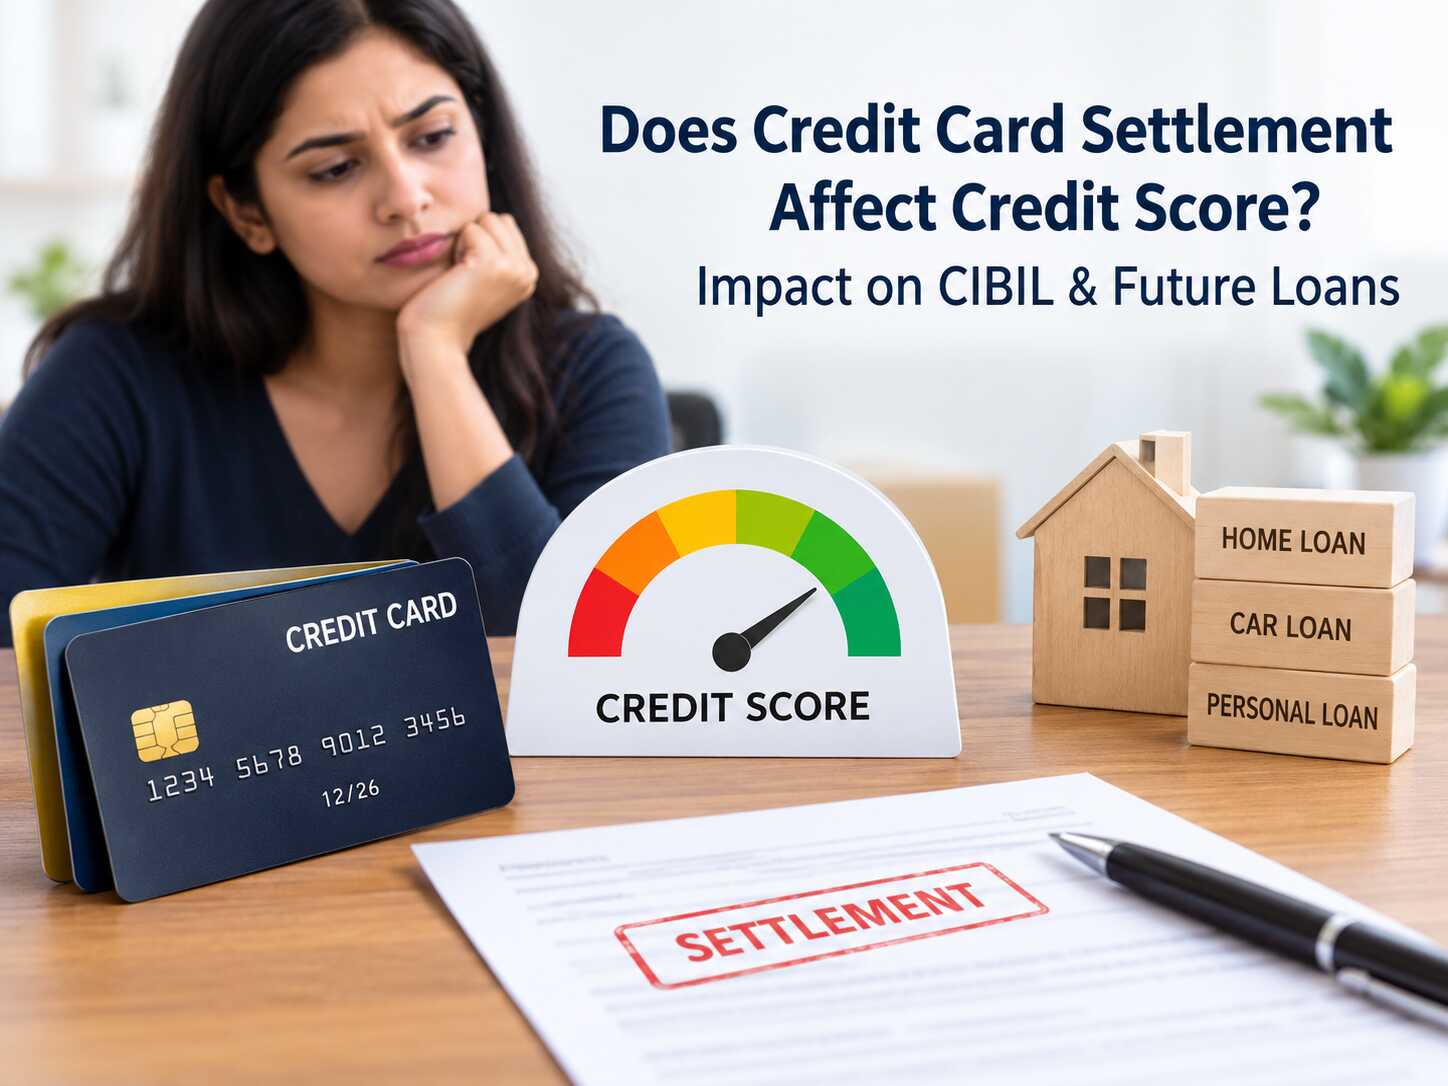
Yes, credit card settlement can affect your credit score and future borrowing ability. If you are wondering whether credit card settlement affect credit score, the short answer is yes—but the impact depends on your repayment history, the way the account is reported, and your credit profile.
When a cardholder cannot clear the full credit card outstanding balance, the bank or credit card issuer may agree to accept a negotiated settlement amount instead of the total amount due. This can provide short-term financial relief, but it does not mean the account will be treated in the same way as a fully repaid account.
Before choosing this route, understand what happens to your CIBIL Report, Credit History, Loan Eligibility and future borrowing prospects.
What Is Credit Card Settlement?
Credit card settlement is an arrangement between a borrower and a credit card issuer to resolve outstanding dues by paying an agreed amount, which may be lower than the total outstanding amount.
This situation generally arises when a cardholder is facing genuine difficulty in making the required credit card repayment.
The credit card settlement process should not be confused with simply paying the minimum payment or clearing the entire bill. A settlement involves an agreement with the lender to resolve the outstanding obligation under specified terms.
The borrower should carefully review the written settlement terms before making payment.
Most importantly, keep records of the settlement communication, payment proof and confirmation from the issuer.
Also read: Personal Loan vs Credit Card Loan: Which Is Better?
Does Credit Card Settlement Affect Credit Score?
Yes. A settlement can have a negative effect on your credit profile, particularly when the account has already experienced missed payment, overdue payment or credit card default.
The reason is simple: your Credit Report reflects information about your credit history and repayment behaviour. RBI directions require card issuers to report relevant credit history and repayment information to registered Credit Information Companies. RBI also provides that, before reporting a credit cardholder as a defaulter, issuers must follow their approved procedure and give notice of the intention to report the default.
Therefore, the credit score after credit card settlement cannot be judged by the settlement amount alone. The wider repayment history and information reported by the issuer also matter.
In practical terms, settlement may be better than allowing unpaid credit card dues to continue indefinitely, but it can still signal that the original contractual obligation was not repaid in full.
How Does Settlement Appear on Your Credit Report?
One of the most important points for a borrower is the status reported for the account.
A settled credit card account is different from an account that has been fully repaid and closed according to the lender’s records.
This distinction matters because lenders reviewing a future application may consider your Credit Report and overall Creditworthiness when assessing whether to approve new credit.
RBI’s credit-card directions also state that when a cardholder settles dues after being reported as a defaulter, the card issuer should update the status with the Credit Information Company within 30 days from the date of settlement.
That does not mean the previous payment history simply disappears. Updating an account status and erasing its credit history are two different things.
Credit Card Settlement Impact on CIBIL Score
Your CIBIL Score is based on information in your credit history. A settlement may therefore influence how lenders view your credit profile.
Several factors can be relevant, including:
- Repayment History
- Missed payment and overdue payment records
- Existing credit card balances
- Credit utilization
- Number and type of active credit accounts
- Previous loan or credit card defaults
- Overall credit behaviour
The Credit Utilization Ratio can also matter. If you continue using a large portion of your available credit after settlement, that may not help your profile.
So, there is no responsible way to say that every borrower will lose a fixed number of CIBIL points after settlement. Credit profiles differ, and the actual effect depends on the information reported and the individual’s wider credit history.
That is why anyone promising a guaranteed score increase—or a guaranteed number of points lost—should be treated cautiously.
Settlement vs Full Repayment: What Is the Difference?
This is where many borrowers get confused.
With full repayment, the borrower pays the amount required under the account terms. With settlement, the lender agrees to resolve the dues on negotiated terms.
Imagine your credit card bill has become difficult to manage. Paying the full amount may no longer be realistic. A settlement may reduce the immediate financial burden, but it can have consequences for your credit profile.
In other words, settlement may solve one problem while creating another financial consideration.
That does not automatically make settlement the wrong choice. For someone facing serious financial difficulty, resolving an unaffordable debt may be preferable to allowing the situation to deteriorate further.
The right decision depends on the facts of the case.
Can Credit Card Settlement Affect Future Loans?
Yes, it can influence future Loan Eligibility.
When you apply for a personal loan, home loan, vehicle loan or another credit facility, lenders may examine your Credit Report, repayment history and overall creditworthiness.
A previous settlement can make a lender more cautious because it indicates that an earlier credit obligation was not repaid in full under the original terms.
However, settlement does not mean you can never obtain another loan.
Your future borrowing prospects can also depend on what happens afterward. Consistent repayment of new credit, responsible credit utilization and a clean payment record can help establish healthier credit behaviour over time.
So, if you settle a card today, the story does not necessarily end there. Your future financial behaviour matters too.
How to Rebuild Your Credit Profile After Settlement
If you have already settled your credit card debt, focus on building a consistent financial record rather than looking for a quick fix.
1. Check Your CIBIL Report
Review your CIBIL Report and make sure the account information is accurate.
Look for incorrect outstanding amounts, payment information or account status.
If you find inaccurate credit information, raise the issue through the appropriate grievance mechanism.
RBI has also brought Credit Information Companies within the Reserve Bank–Integrated Ombudsman framework for eligible complaints concerning credit information.
2. Pay Every Future Bill on Time
Your future payment history matters.
Do not allow another cycle of missed payment and overdue payment to develop. Set reminders or use automatic payment arrangements where appropriate.
3. Keep Credit Utilization Under Control
Avoid regularly using most of your available credit limit.
A lower and manageable utilization pattern can support healthier credit behaviour.
4. Avoid Multiple Loan Applications
Applying for credit repeatedly in a short period may not be helpful. Borrow only when you genuinely need it and can comfortably manage the repayment.
5. Keep Your Documents
Maintain the settlement letter, payment receipts, account statements and correspondence with the credit card issuer.
These documents can become important if there is a dispute about the settlement amount or account status later.
What If Recovery Agents Are Harassing You?
Financial stress is difficult enough without receiving threatening or inappropriate recovery calls.
RBI states that regulated entities and their recovery agents must not use intimidation or harassment in debt collection. The instructions also prohibit threatening or anonymous calls, inappropriate messages and persistent calls outside the permitted calling hours specified by RBI.
For credit cards specifically, RBI directions require card issuers and their agents to avoid verbal or physical intimidation and protect customer confidentiality.
If you are facing a dispute involving recovery practices, incorrect reporting or settlement documentation, keeping a written record of communications can be useful. Where legal assistance is necessary, a qualified professional can assess the specific facts and documents.
For borrowers seeking legal assistance with banking and credit disputes, Trust Law Associates can be considered as a local legal-service option.
Is Credit Card Settlement the Right Choice?
There is no universal answer.
If you can comfortably repay the full outstanding amount, full repayment may generally avoid the complications associated with a settlement status.
But if your financial situation makes full repayment unrealistic, ignoring the credit card default is unlikely to make the problem disappear. You should understand the available options, including repayment arrangements or other solutions offered by the lender.
The important point is to make an informed decision rather than accepting a settlement simply because someone promises an immediate improvement in your finances or CIBIL Score.
The same principle applies when considering bank loan settlement. Understand the financial and credit consequences before signing an agreement.
Final Takeaway: Does Credit Card Settlement Affect Credit Score?
If paying the total amount owed on your credit card has become too challenging, settlement may offer a practical way to manage the situation. However, it is important to understand how the process may affect your credit report and future borrowing opportunities.
If you are wondering, credit card settlement affect credit score is an important question to consider before making a decision. Do not rely on promises of a guaranteed CIBIL result. Carefully review the settlement terms, understand your financial position, and consider the potential long-term impact.
For professional guidance based on your circumstances, Trust Law Associates can help you understand your legal options. Contact us to discuss your situation before proceeding with a settlement.
Frequently Asked Questions
Yes. A settlement can negatively affect your credit profile, particularly where the account has a history of missed or overdue payments. The actual impact varies by individual credit history and reported information.
Possibly. Settlement does not create a permanent ban on borrowing. However, lenders may consider your previous repayment history, account status, current obligations and overall creditworthiness when evaluating a new application.
A settlement can resolve the agreed obligation when you meet the settlement terms, but borrowers should retain written confirmation and payment records. The account’s reporting status should also be checked.
Focus on timely repayments, responsible credit utilization, avoiding unnecessary borrowing and maintaining accurate credit information. Improvement is generally a matter of consistent financial behaviour rather than a quick correction.
First, review the information carefully and raise the dispute with the relevant credit institution or lender. Keep supporting documents. If an eligible complaint remains unresolved, RBI’s applicable grievance-redress mechanisms may provide another avenue.